Loading... Today
-- 0
-- 0
The Print Times
Mumbai: Lodha Developers reported its best-ever quarter in Q1 FY27, with revenue rising 43% year-on-year to INR 5,000 crore. Adjusted EBITDA increased 79% to INR 2,150 crore, with the EBITDA margin improving to 43% from 34.4% a year earlier. Profit After Tax (PAT) stood at INR 1,370 crore, more than double the INR 680 crore reported in Q1 FY26, with a PAT margin of 26.9% compared with 18.6% in the corresponding quarter.
Lodha, India’s leading real estate developer, is driven with the passion of building world’s finest developments across its residential, commercial and warehousing portfolio. The company has delivered ~110 million square feet of real estate and is currently developing more than 130 million square feet under its on-going and planned portfolio.
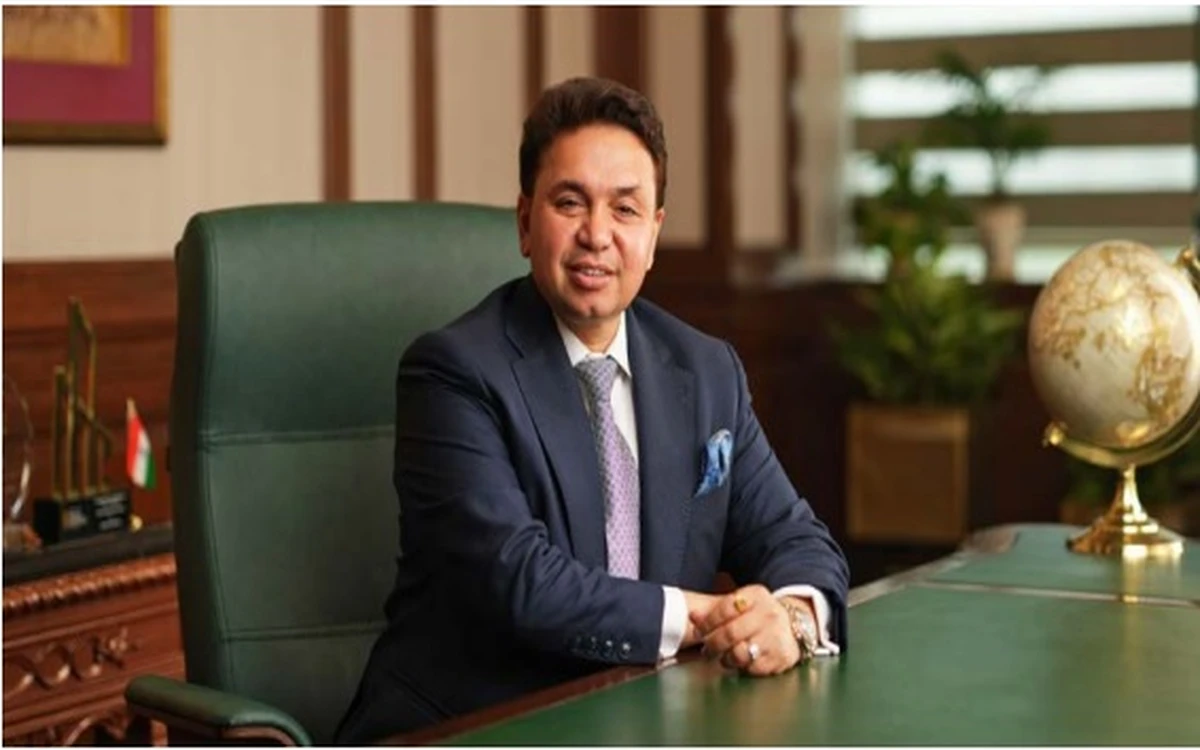
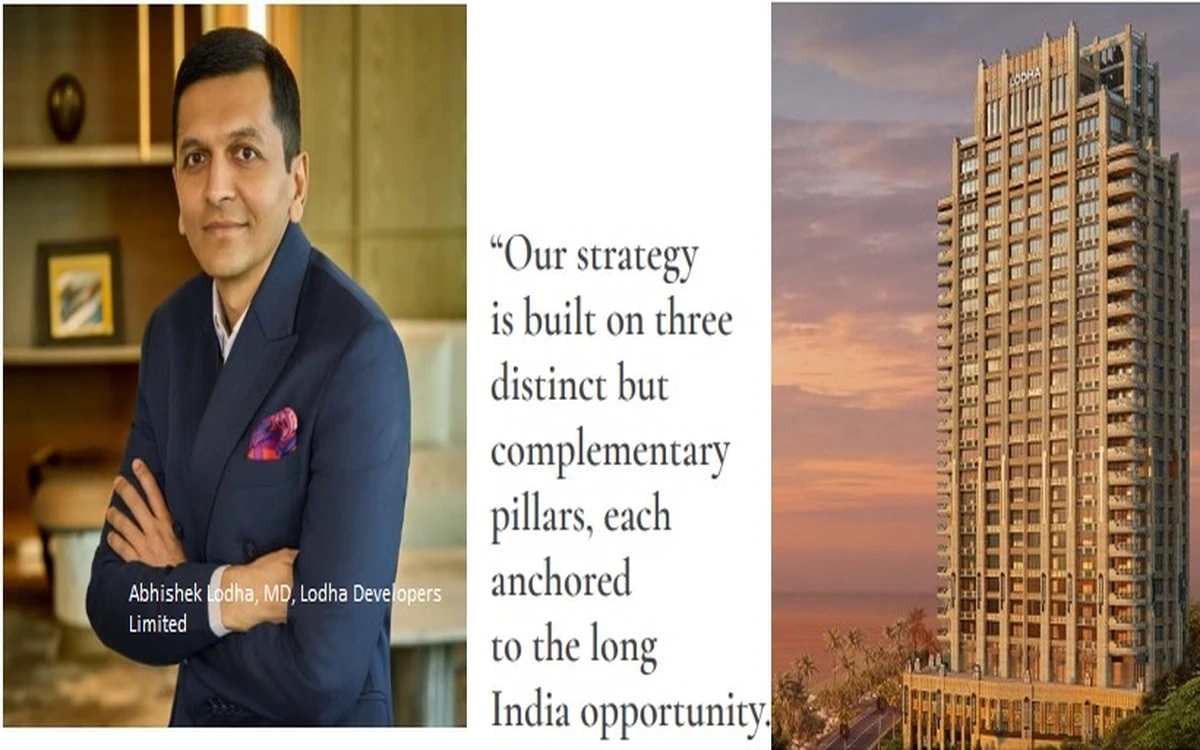
Abhishek Lodha, Managing Director, Lodha Developers Limited, said the company wants investors to assess its performance primarily through audited accounting profit after tax and operating cash flow.
“Profit and cash together are the true reflection of any business,” Lodha said, while cautioning that accounted profit would not necessarily follow a quarter-on-quarter trend because of the nature of percentage-of-completion accounting.
He said quarterly revenue depends on factors including receipt of minimum sale proceeds from buyers, construction costs incurred during the quarter and the timing of land or annuity transactions. “Our commitment of 20% PAT growth is an annual guidance, not a quarterly one. Please do not annualize any single quarter,” he said.
Strong Cash Generation and Lower Debt
Lodha reported collections of INR 4,210 crore during Q1 FY27, up 46% year-on-year. This translated into operating cash flow of INR 1,890 crore. After investments, the company reduced net debt by INR 450 crore, bringing it below INR 5,000 crore.
Net debt to equity stood at approximately 0.2x, against the company’s self-imposed ceiling of 0.5x. Net worth was just under INR 25,000 crore, while the average cost of debt remained at 7.8%.
“Funding all of our growth from operations while simultaneously deleveraging is, in my view, the genuine signal in this quarter, more so than any other number,” Lodha said.
Pre-sales during the quarter stood at INR 4,630 crore, an increase of 4% year-on-year. The company said the lower growth was a result of limited residential launches during the quarter rather than a deterioration in underlying demand.
Residential Demand Remains Strong
According to Lodha, the residential business remains in strong shape. The company had deliberately postponed launches during Q1, with new launches normally contributing around one-third of pre-sales.
Only one new residential phase in Mumbai, covering approximately 0.4 million sq. ft., was launched during the quarter.
“This was a decision, not an outcome,” Lodha said, explaining the 4% year-on-year growth in pre-sales despite the limited launch activity.
The company expects launches to accelerate from Q2, with its FY27 launch calendar comprising more than 20 projects and phases with approximately INR 25,000 crore of Gross Development Value (GDV). The launch programme includes the company’s first launch in NCR, along with continued expansion in Bangalore and Pune.
Lodha reaffirmed its FY27 pre-sales guidance of INR 24,000 crore and expects the first half of the year to contribute 40–42% of the full-year target. The company said it is targeting pre-sales of INR 5,000 crore or more in Q2.
Premium and Luxury Housing Drive Demand
Lodha said demand in the residential market remains solid, particularly for larger and stronger brands. The company highlighted a continuing shift towards premium and luxury housing.
“Housing is no longer seen as just the bare necessity of shelter, but a lifestyle-enhancing investment decision. This has led to a significant expansion in the premium and luxury segment in the industry,” Lodha said.
Premium and luxury segments accounted for almost 60% of the company’s sales during Q1 FY27.
The company also pointed to increasing consolidation within the industry, with consumers showing a preference for established and trusted brands. Lodha said branded players accounted for almost 30% of the MMR market by the end of 2025, compared with less than 20% five years earlier, and estimated that this could reach 40–45% by the end of the decade.
Middle East Conflict and Cost Outlook
Lodha said the Middle East conflict continued to affect sentiment among Middle East-based NRI buyers, who account for approximately 4–5% of the company’s sales and around one-third of its overall NRI business.
However, the company said the demand impact remains moderate and expects uncertainty abroad could encourage some NRIs to secure a home base in India.
On costs, Lodha said its supply chain is approximately 95% domestic and that availability has not been an issue. However, energy-intensive input costs have increased.
“If this situation persists for a full year, we would expect project construction cost to rise by between 1% to 1.5%, with spread across a 3 to 4 year build period and assuming no price response; project level EBITDA impact of between 35 to 75 basis points,” Lodha said.
The company noted that overall construction cost inflation since April 2022 has been approximately 3% per annum.
Land Monetisation Remains a Key Business Pillar
Lodha said land monetisation is a planned and recurring component of its business rather than an exceptional item.
The company currently holds approximately 660 acres in its data centre park. Of the first phase covering 370 acres, around 130 acres has already been monetised. Lodha intends to monetise a further approximately 150 acres over the next three to four years.
The company expects this to generate close to INR 10,000 crore of sales, while additional optionality exists through approximately 300 acres.
Overall, Lodha expects land to contribute between INR 2,000 crore and INR 3,000 crore of sales annually over the next several years.
Data Centre Business Gains Momentum
The company highlighted significant progress in its green data centre park at Palava, including the entry of Digital Edge India, a joint venture between Digital Edge Singapore and the National Infrastructure and Investment Fund, joining AWS and STT.
The transaction was concluded at approximately INR 420 million per acre, compared with INR 210 million per acre in previous transactions during calendar 2025, representing almost a doubling of value in less than 12 months.
Lodha said the value of its land at Palava has increased more than 15 times over the last five years.
The data centre park has approximately 3 GW of power availability, five fibre-optic routes, five transmission lines and approval under the Maharashtra Green Integrated Data Centre Policy.
Of the approximately 660 acres, around 130 acres has been sold, while a further 150 acres is expected to be monetised over the next three to four years at an average of approximately INR 600 million per acre. This is expected to generate approximately INR 9,000 crore of further sales from Phase 1.
The proceeds are expected to fund the development of approximately 1 GW of powered shell across around 90 acres, which the company expects will generate more than INR 2,000 crore of annual rental income by FY32.
RentCo Business Targets Significant Growth
Lodha said its broader annuity business had an exit run rate of approximately INR 300 crore as of June, excluding any contribution from data centres.
The company is targeting more than INR 3,000 crore of annuity income by FY32, representing a tenfold increase. Of this, more than INR 2,000 crore is expected from data centres, INR 600 crore from retail and offices, and approximately INR 400 crore from warehousing and industrial assets.
The company said these estimates are based on land already acquired and development activity already underway and do not include further incremental land additions.
Medium-Term Growth and Capital Allocation
Lodha reiterated its guidance of approximately 20% PAT growth over the medium term, targeting PAT of more than INR 8,500 crore by FY31. The company also aims to improve return on equity from approximately 16% in FY26 towards 20%.
The development business is expected to become effectively debt-free over the next two to three years, while net debt-to-equity is expected to remain below the company’s 0.5x ceiling.
“Our capital allocation hierarchy is clear and publicly stated: fund opportunities where there is brand fit and execution capacity, about 20% ROCE in DevCo and about 15% in RentCo, a regular dividend at 15% to 20% of PAT, thereafter debt reduction and thereafter, any surplus towards buyback or special dividends,” Lodha said.
The company said its development business has an unsold GDV of approximately INR 2 trillion, providing a substantial growth runway for the foreseeable future.
Outlook
Lodha said it remains focused on balancing sustenance sales from existing projects with new launches. Historically, around 65–70% of its business comes from existing projects, while 30–35% comes from new launches.
Most of the new launches for FY27 are expected in the second half of the year, coinciding with the festive season. The company has planned launches in Bangalore, Pune, NCR and MMR and remains confident that sustained sales from existing projects combined with new launches will support its annual goals.
“We are not raising guidance on the strength of one quarter. We will endeavour to outperform,” Lodha said.
last week
Total Views : 37
last week
Total Views : 37
last week
Total Views : 35
last week
Total Views : 28
last week
Total Views : 40
last week
Total Views : 38